All Categories
Featured

Ensuring Final Expense Insurance for Veterans and Spouses
Table of Contents
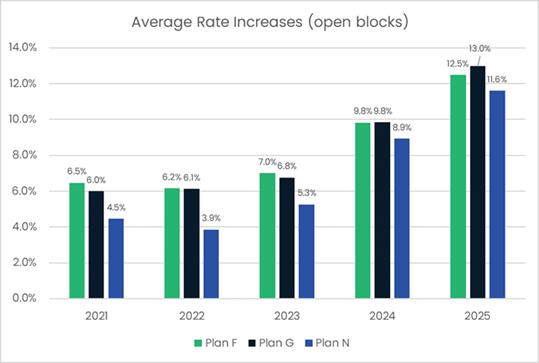
Medicare Supplement plans cost $180 monthly, usually, in 2026. These plans have the finest protection for elders brand-new to Medicare. A Medigap Plan G policy covers almost all the expenses you're normally accountable for with Medicare, other than for the $283 annually Part B deductible. Medigap Strategy F generally does not make sense economically.
Insurance GlossaryA high-deductible Strategy G expenses just $52 monthly, usually. That does not always make it an excellent deal. That's due to the fact that you have to pay $2,950 for healthcare each year before protection begins for either strategy. You're much better off with a regular Plan G Medigap policy if you expect to consistently need a lot of medical care.
F$ 227G$180N$137C$243B$205D$198A$168M$154L$134K$87High-deductible F$ 58High-deductible G$ 52Show All Rows Just how much you pay is based upon several factors, consisting of: The strategy you select The business you choose Where you live Your age and gender (normally) Discounts you receive When you enrolled Massachusetts, Minnesota and Wisconsin have various Medicare Supplement strategies than the rest of the country.

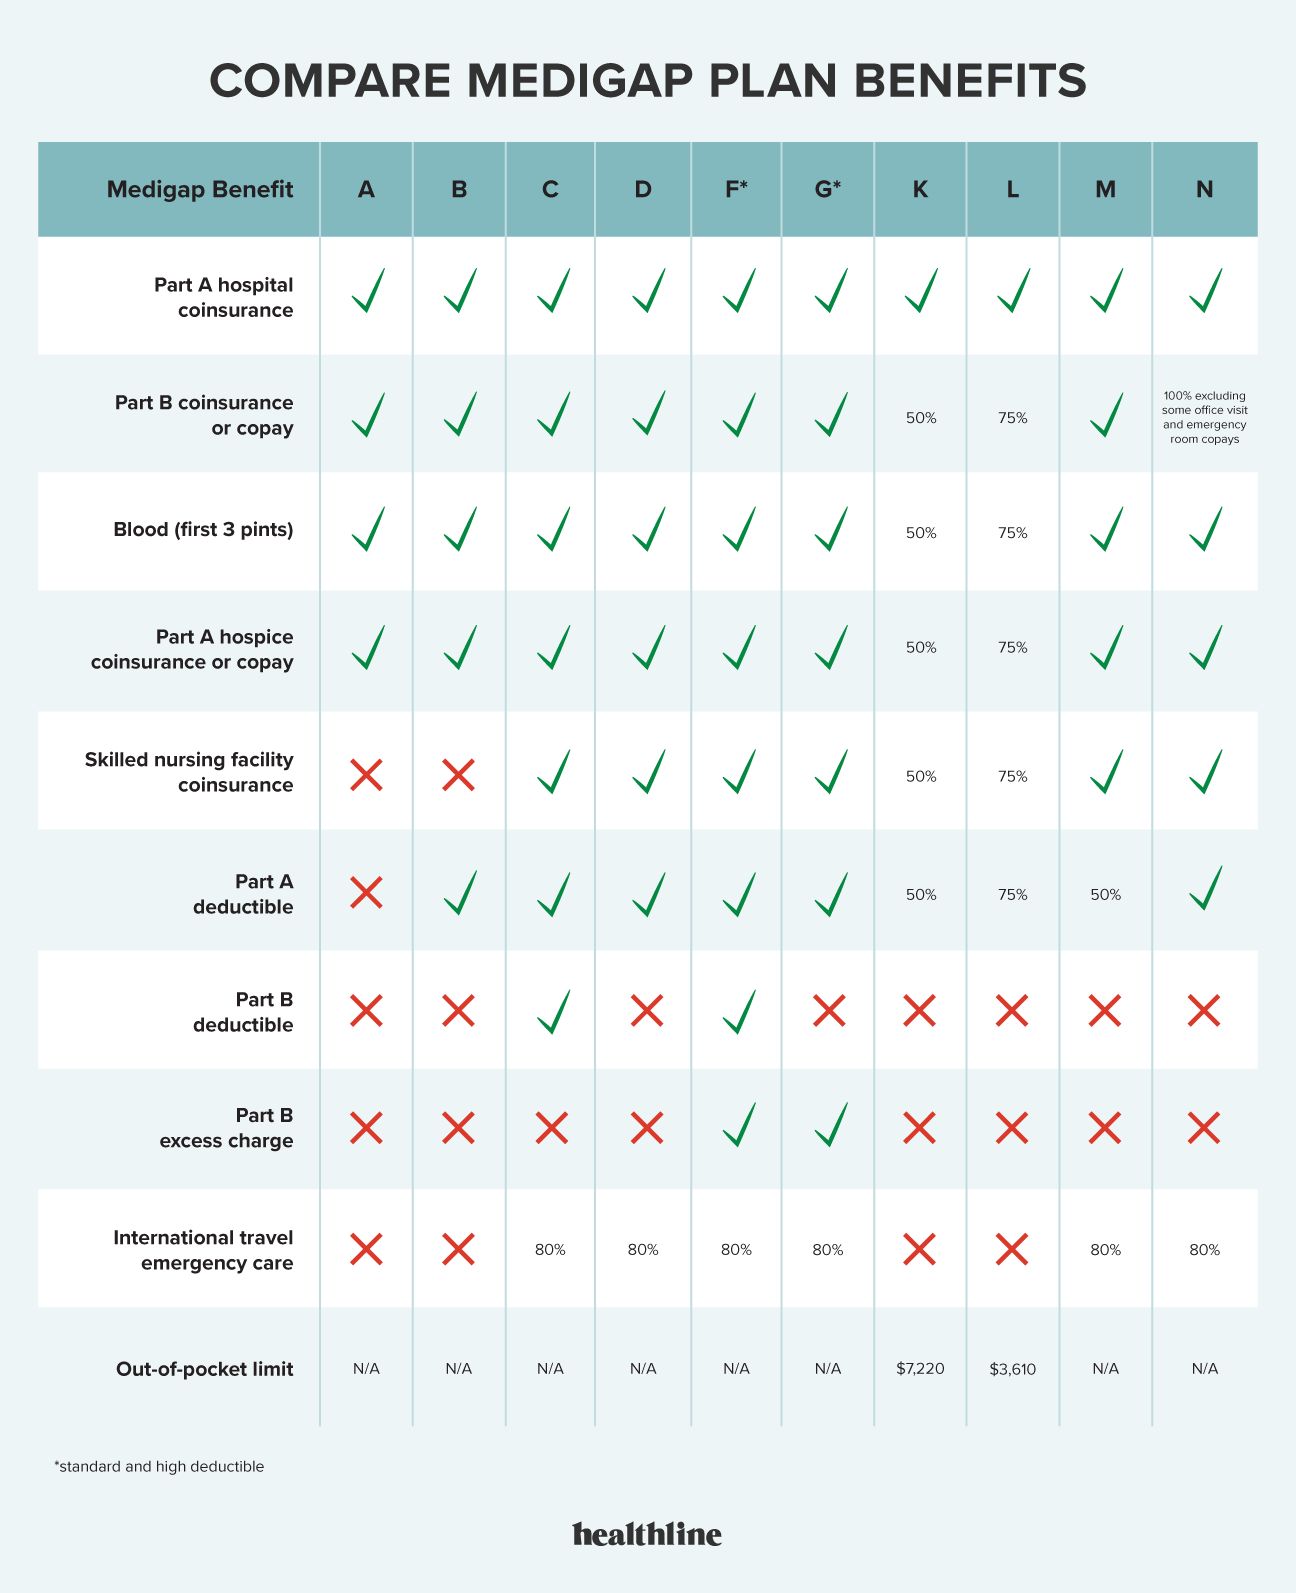
In Massachusetts, you can select between 3 different types of Medigap plans: Core, Supplement 1 and Supplement 1A. In Minnesota, the very best Medicare Supplement choice for many people is the Basic plan. This plan offers a comparable level of protection as Medigap Plan G. The Basic plan covers nearly all the expenses you are accountable for with Original Medicare (Parts A and B).
Essential Strategies for Selecting Burial Insurance Coverage
The Extended Basic strategy provides much more coverage. It pays for your Medicare Part A deductible, foreign travel emergency situations, preventive services not covered by Medicare and extra costs you're accountable for if your physician doesn't accept the rate set by Medicare. This strategy is generally not a good choice due to the fact that of its high expense.
Insurance GlossaryTo put it simply, you can construct your own Medigap strategy by including coverage additionals to your policy. Base plans require to cover particular advantages like your Part A (health center care) coinsurance or copay, 175 days of psychological health inpatient care and some of the expenses you are accountable for paying with Part B (physician sees).
Lots of business let you modify your policy with protection bonus, generally at a higher cost. You can pick a Base strategy choice with a lower month-to-month rate, however you'll pay more when you visit the medical professional. High-deductible strategies: You'll pay more before coverage starts. 25% cost-sharing plans: You'll pay roughly 25% of your medical costs, similar to Plan L.
Best Strategies for Getting Individual Health Insurance Quotes
Select a Medigap policy by comparing strategy advantages and expenses versus the medical care you expect to need. Try to match your protection with your specific medical needs. For example, it might not make sense to get a policy with excellent coverage like Plan G or F if you remain in health and you do not go to the medical professional frequently.
If you have a special needs or ongoing health problem, or you just want the peace of mind of having great protection as you get older, you should select a plan with much better coverage like G, F or N. Even though these plans have greater typical rates, you'll conserve cash when you go to the medical facility.
If you want the versatility to easily change from an inexpensive plan to a strategy with much better protection, Blue Cross Blue Guard is the very best alternative. Its Blue to Blue guideline suggests you can switch Medigap strategies at any time without paying a higher rate since of your age or health status.
Remember, plans have the exact same coverage if they have the exact same letter. A Strategy G will have the very same protection regardless of whether you purchase it from AARP/UnitedHealthcare or Blue Cross Blue Guard.
Comparing PPO Vs HMO Health Plans for 2026
You don't want to choose a business that has bad client service, since that can cause issues down the roadway. Before you pick a Medicare Supplement company, check to see if you can get discount rates. Family discounts for married couples, civil partners and extended family members who live together are a typical way to save.
Depending upon where you live, you may also have the choice to select an inexpensive Medicare Select strategy. These policies have the exact same protection as a regular Medigap plan, however they restrict you to a network of physicians like an HMO. You no longer require a broker to purchase a Medigap policy.
Bear in mind that your Medigap costs depend in part on where you live, and plan schedule varies by county. You can also purchase a Medicare Supplement strategy directly from a company's site. This is the quickest route to getting a Medigap policy. It's typically a good option if you feel confident that you have actually recognized the ideal plan and company for you.

Latest Posts

Direct Consumer Advice for Life Insurance Selection
Ensuring Final Expense Insurance for Veterans and Spouses
Choosing 2026 Medicare Benefits